

This piece, in a slightly more compact version, was published and indeed commissioned by Tim Purcell at The Lykeion, an excellent financial commentary website last week. I am reprinting an expanded version here for you, with thanks to The Lykeion team for the initial encouragement.
Germany is a complicated place for non-Germans, especially Anglo-Saxon non-Germans to understand. With Germany front and centre of the storm unleashed by the energy crisis and the current Government - a patchwork coalition of Social Democrats (SDP), Green (Die Grünen) and Liberals (FDP) - evidently hell-bent on sticking to its anti-nuclear policy, the outside world is wondering whether the world’s fourth largest economy is about to head into a disastrous winter which may see whole scale destruction of businesses and its industrial base. It feels a little like watching a car crash in slow motion.
I spent the filet years of my adult life from 1987 to 2014 living and working in Germany, based in or close to the Bavarian capital of Munich. I have been involved with both private and public companies, was one of the founders and Chairman of the country’s first publicly listed restructuring holding companies and have been advisor to and responsible for the financing of countless midmarket companies and their owners over the past three decades. My wife is a German national and my children were all born there so I have more than a passing understanding of how the game is played in the BRD. I was part of a group of Mittelstand (private midmarket “family businesses”) experts who were regularly invited to meetings with the then Chancellor Angela Merkel between 2008 and 2010 to provide a counter-balancing voice to the big beasts from the companies at the top of the industrial pyramid with whom she usually consorted. From that perch I got to witness the unfolding disaster of the GFC and Chancellor Merkel’s reaction to it close up. That experience alone demonstrated that principles in politics are about as robust as balsawood tennis rackets and as much use.
The German Business Model
The question of how Germany can survive the collapse of not just one but all three of the key elements of its business model is a fascinating one that cannot be answered by applying simple Anglo-Saxon business logic. Germany doesn’t work like that. It may look as though the country is hurtling pell-mell towards the buffers at the end of the train terminus and that it will all end in a wreck of epic proportions, but I wouldn’t bet on it happening quite yet or quite as dramatically as the catastrophe porn Cassandras on Twitter might have us believe.
The three elements of the hyper-successful German post-war business model are
Very low national security costs (outsourced deliberately by the Allies after WWII and happily maintained by the German political classes ever since as it meant they could use the dosh to build out a generous welfare system instead of investing it in tanks and boots on the ground) allowing a total focus on building export markets at the expensive of domestic consumption and compounding an enormous current account surplus at the same time;
Cheap money through its highly fragmented banking system backed at the top by Government guarantees (until the early 2000s ) and later after the introduction of the Euro a much weaker currency than the DM would ever have been allowed to be on its own, translating into cheap debt funding and not much need for equity or public markets;
Cheap energy from Russia and nuclear power from France / Switzerland whilst allowing the country to virtue signal about its Energiewende and Green Carbon Emission compliance, possibly the single largest misallocation of public funds since the Tower of Babylon was constructed.
As each three of those boosters of national prosperity now appear to be being dismantled at the same time and at high speed the fragility of the German economy - its business model if you will - is being brutally exposed. Zoltan Poszar recently wrote in his excellent “War and Industrial Policy” note that
“Minsky moments are triggered by excessive financial leverage, and in the context of supply chains, leverage means excessive operating leverage: in Germany, $2 trillion of value added depends on $20 billion of gas from Russia...
...that’s 100-times leverage (see the last chart below) – more than Lehman’s. “
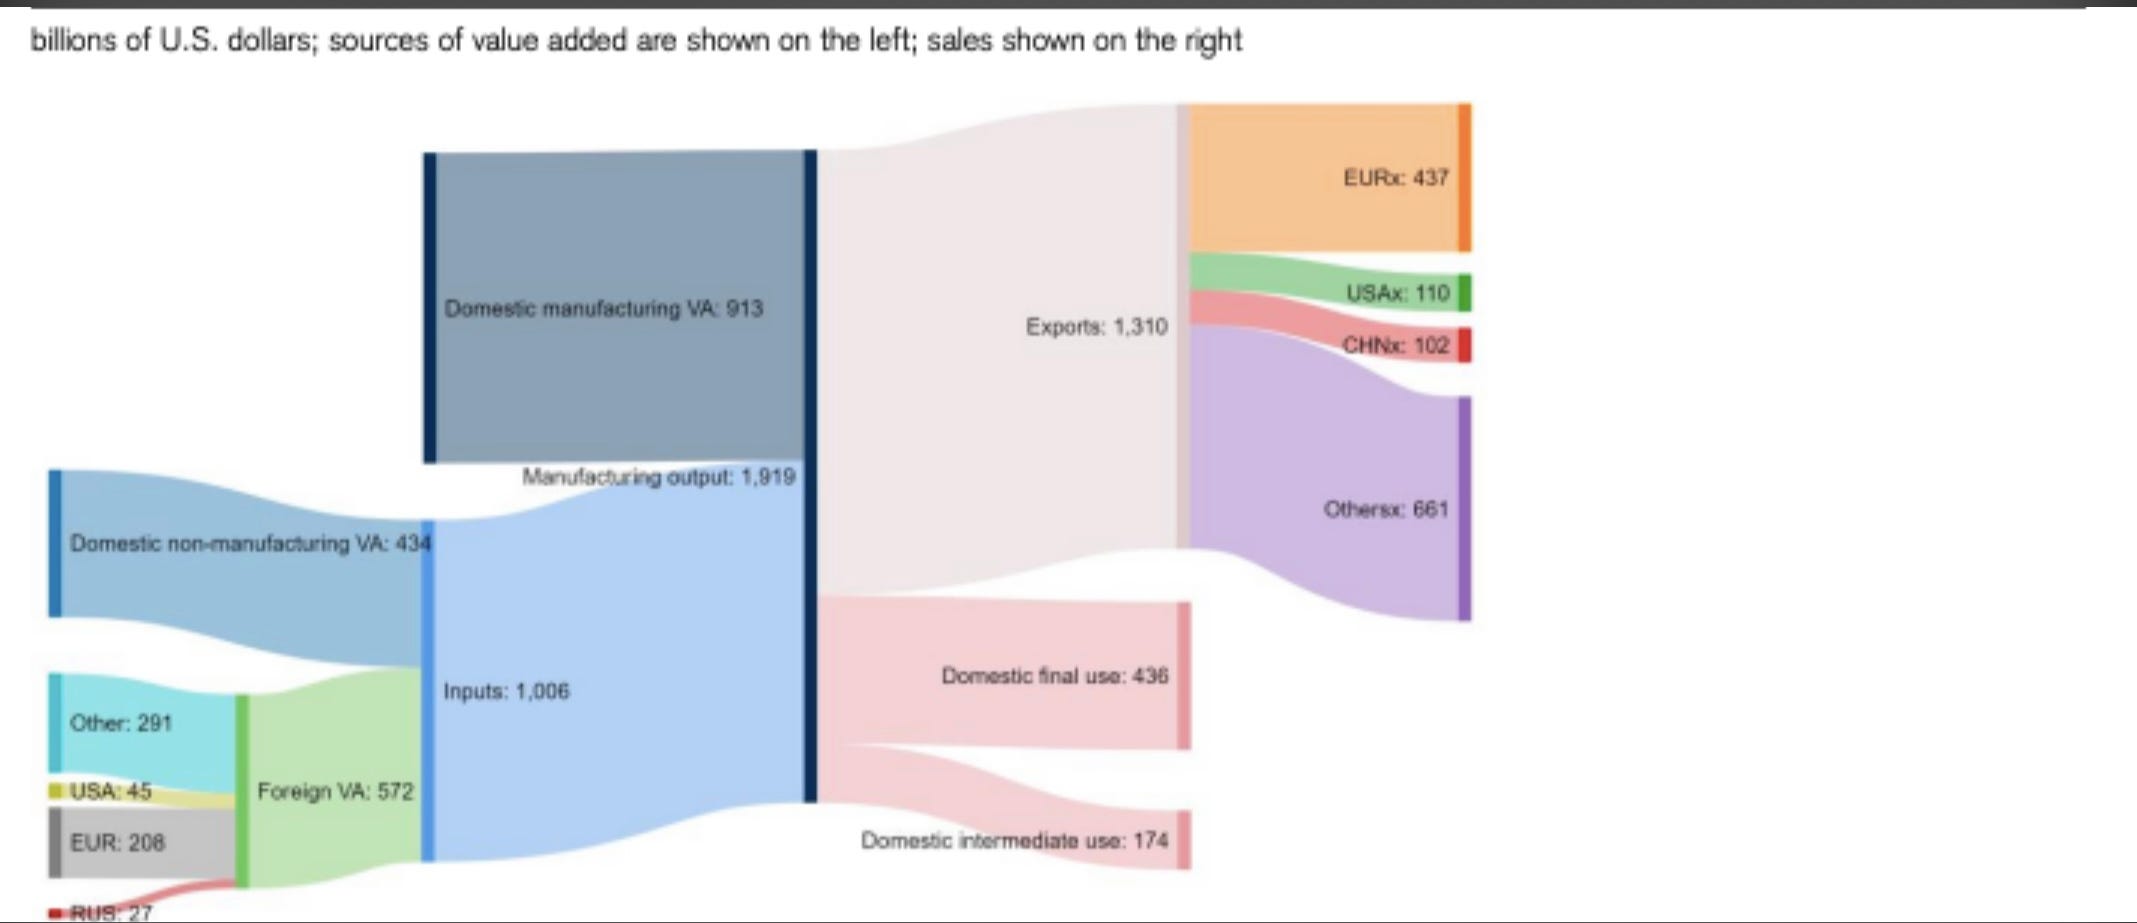
Source: [CS The G-SIB of Commodities April 2022]
Sozialer Frieden - The Ultimate Goal
The first thing to know about Germany is that the commitment to social stability from every constituent of the country’s institutions - public and private - is overwhelming. However much Unions and Employer Federations may be at each others throats in public, no matter how antagonistic the parties may appear on the floor of the Bundestag, no matter what the issue of the day with which parliamentarians seek to score points off each other, behind the scenes everyone works together to preserve social peace when push comes to shove. That drive to consensus subsumes pretty much every divide and takes no prisoners in its overriding objective - not the Constitution, not previous promises made with regard to the sanctity of the currency, nothing is so sacrosanct that it cannot be sacrificed on the altar of consensus to appease the fearful Gods of Social Disorder. We all know what happened last time that was allowed to happen and that lesson is baked into the DNA of every German in a position of responsibility. Kant’s Categorical Imperative - which states that every action taken must conform to the principle of being turned into a maxim apllicable to everyone in order to be morally correct and which today is used as a short hand for the superiority of “common good” actions over private individual and by default selfish ideas of personal freedom - is the bedrock on which the German, often deeply authoritarian, consensus is built. When you read about the aggressive self-righteous lynch mob fury against the unvaccinated or the hated “Querdenker”, then you can find hefty strands of Kantian moral superiority showing up on the PCR test.
So the current crisis is going to be - is being - tackled in exactly the same way. Public Private Partnerships and reframing of legal, financing, regulatory norms the primary result of which will be to transfer the risk and cost of social stress and unrest to the national balance sheet: Effectively spending their way out of the private sector deficits created as first, second and third order consequences of their own face-saving policy choices.
And bearing the brunt of all this idiocy is the German Mittelstand - that fabled population of hardworking, conservative manufacturing businesses that form the backbone of Germany’s economy and of whom they are inordinately proud and everyone else is inordinately envious.
Mittelstand Primer
In order to understand the Mittelstand you have first to understand the unique regionality of the BRD and its federal system of government which devolved a great deal of power and autonomy to the individual states. Each State has its own regional capital replete with its own banking system headed up by the regional Landesbank as well as a raft of special purpose financing institutions (Buergschaftsbanken and the like) whose purpose is to provide access to capital and capital-like financing options to local industry. Add to this the fact that Germany is significantly over-banked, with local Sparkassen (Savings Banks) and VR Banken (Cooperative Banks) along side Private Banks (like Deutsche and Commerzbank) overflowing with deposits and backed by implicit State guarantees (the explicit guarantees disappeared in 2008/09 as a result of Basel III and EU anti-subvention rulings) with implications for cost of and access to capital, then you will understand how Germany is institutionally constructed to provide support to industry in a way no other country is.
Then you have to understand that German lawmakers - despite the appearance of highly regulated and worker-friendly employment laws (which are real and make restructuring a nightmare) - have in the past moved quickly to create some sort of flexibility (see Kurzarbeit Gesetz in the wake of the 2008/09 crisis) to help businesses navigate disruptive periods. The last thing the parties want is a shift of employees to unemployment status, so they work with the Unions and the representative employer federations to come up with programs that allow the system to breathe and by and large these work very well.
This suspension of whole blocks of the legal code deemed to be inconvenient in a crisis extends to insolvency laws as well. Even after the reform of the old, draconian bankruptcy laws at the turn of the millenium, Germany’s new-ish insolvency laws are harsh and impose hefty personal liabilities on company directors if they can be proven to have violated the tight liquidity and solvency rules. Trading whilst insolvent is a criminal offence and can lead to gaol time. Consequently, prudent directors and managers err on the side of caution and move quickly to register companies for preliminary administration thereby oft sealing their fate prior to liquidation. In order to avoid a wave of insolvencies during the COVID restrictions, lawmakers suspended most of the requirements to file for insolvency and removed liability penalties from directors. This suspension had the wished for effect of preventing wholesale insolvency protection applications (with which the under-staffed and furloughed courts would not have been able to process anyway). It is as sure as eggs are eggs that this market-distorting blanket solution will be thrown over the country once again in order to avoid a disaster as the winter crisis cranks up stress levels which even the blindest of observers will be able to link directly back to the Government’s own intransigent policies. The last years have seen the overall number of corporate insolvencies trending down as cheap credit, rising global asset prices and a robust demand for the sort of stuff that Germany produces in significant quantities, keeps even leeky boats afloat, but this largely homemade crisis of energy costs, threatens to turn that trend on a sixpence and see insolvencies spike.
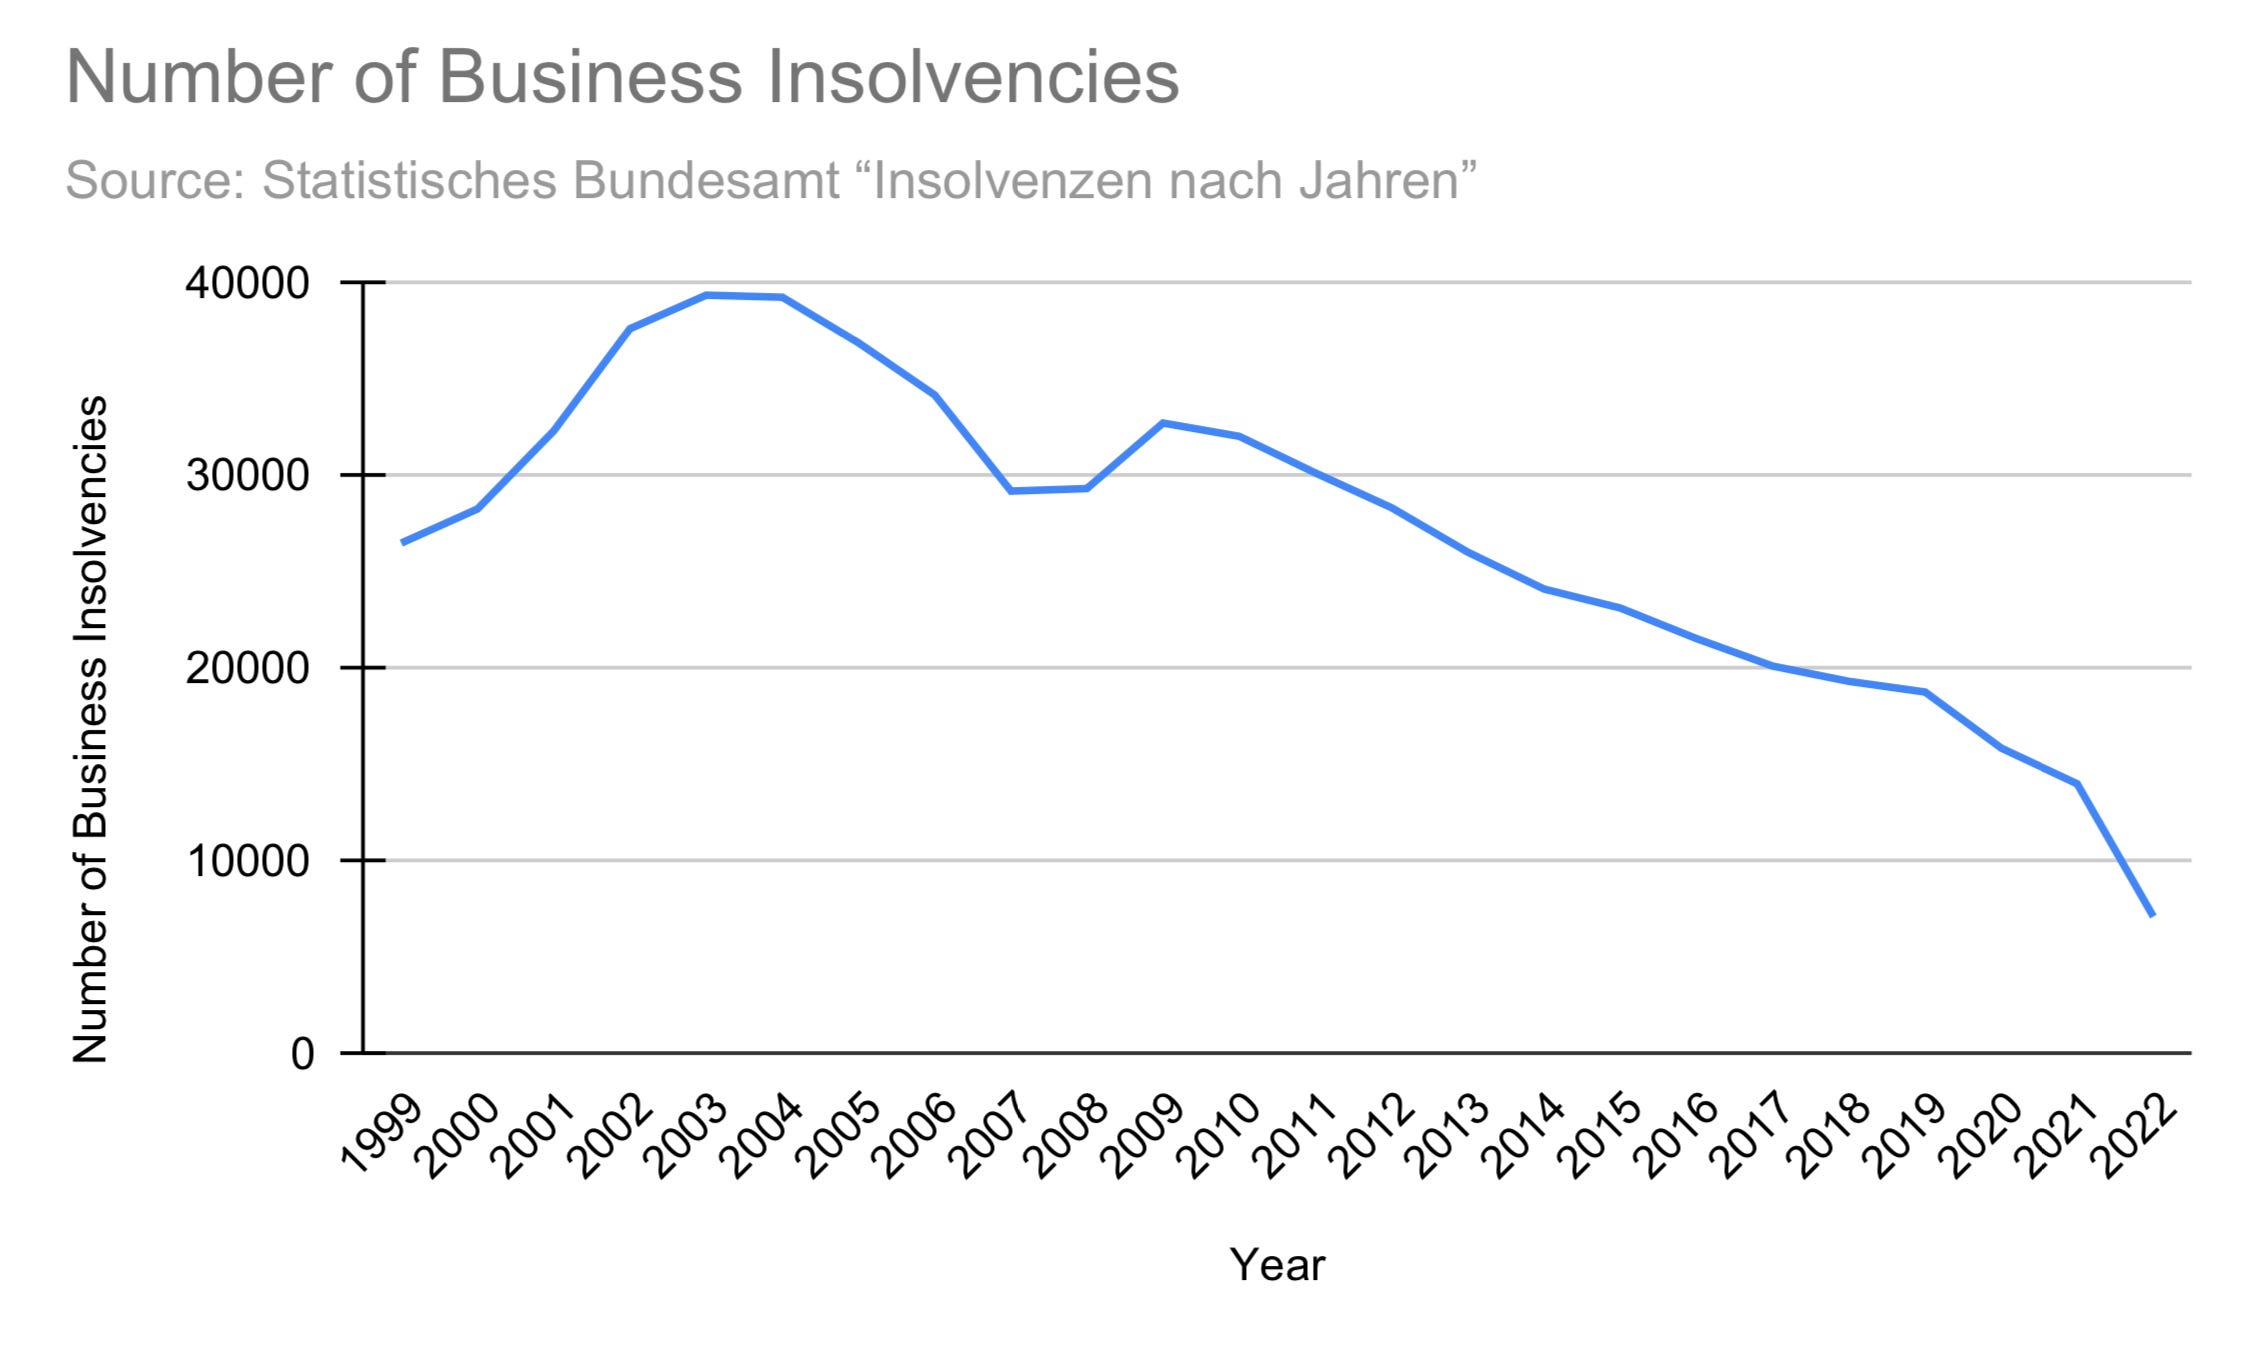
In fairness, it must be stated that the series only runs to the end of June and the numbers are not showing anything out of the ordinary so far. Certainly a number of prominent insolvencies over the past week has made the German public sensitive to this topic and may be the canaries in the mine, which to mix my metaphors with gay abandon, put the cat amongst the pigeons and may mark the beginning of a dramatic upturn. The appearance of the “Pleiteticker.de” website which rather gruesomely publishes a daily death count of business and an accompanying timeline of bust companies and public services is a sign of increasing, possibly morbid, fascination with the German version of the Doomloop.
Additionally, there are huge loan and credit insurance programs run by the KfW (the original Bank for Reconstruction) which has now become the conduit of choice for dispensing government funding and largesse in crises. Expect to see a new program for industry to help mitigate the gigantic, potentially economy-breaking increases in energy costs on top of the €65 billion for private households announced a few weeks ago. This program will be managed and distributed by the KfW, if they don't choose a tax credit route. This lecture by the ever-prescient Russell Napier (for the link to which I am indebted to a long time reader of Pitchfork Papers)
sets out the case for the repatriation of credit allocation powers to the national governments from the Central Banks, where they have been vested for the best part of the last forty years. Germany is currently making the most egregious use of directing industrial and consumer credit creation through overt guarantees to banks and other ingenious forms of largesse designed to keep the show on the road with increasingly worthless money.
So German industry is wrapped in a cocoon of regional and national capital, insurance and export guarantees, facilities, and grants along with an arcane and complex tax and legal system impenetrable to outsiders but designed to allow the appearance of upholding workers' rights and keeping the capitalists in their place but internally creating plenty of room for manoeuvre. Expect to see these activated and expanded on steroids by the current government whose only response to anything is pile on the debt to shield the citizenry from the consequences of its own intransigent stupidity.
Additionally there is a current concerted appeal to the old wartime solidarity in which the German people came together in the aftermath of the last conflagration to share pots and pans and provide each other with camaraderie in the midst of suffering, hunger and hardship. It is hard to believe that the modern day aging German population, with its sense of entitlement, reliance on a generous welfare system and sense of superiority, not to mention their hypochondria on full display during the past two and half years, will stand for much discomfort to stand strong with the poor Ukrainians. But you never know.
What Happens Next
There are a few things which the last few weeks and months have demonstrated to us:
Green Dogma versus the National Stability Imperative: Germany will not be switching on its nuclear power generators any time soon and not at all under this coalition. The Greens would rather eat radioactive waste than ensure the country’s energy security and renege on the “Atomkraft - Nein Danke” slogan that made them famous.
Europe’s largest economy is currently playing a game of chicken of epic proportions - Green Chicken if you will, but not the one we have grown to love and admire as a doyen of energy market commentary . One of the cars being being driven at full speed from the left by the Green Party leaders whose party rose to national prominence and whose entire brand and identity are built on its opposition to nuclear power. “Atomkraft - Nein Danke!” is what the Green Party stands for and they have a much stronger sense of their brand than the weaker SDP. Their base expects them to stand strong for the Green Utopia they have been clamouring for for half a century. Hurtling down the road at them from the right is a car full of crisis accelerants which we can happily call the reality car. The question is who is going to blink first: will the crisis car veer off the road into the ditch and run out of steam leaving the Greens vindicated having stuck to their principles? Or will the Greens buckle and with the usual political wailing, gnashing of teeth and reverse engineering of their previous logic, be forced into a humiliating acceptance of nuclear energy “for the time being”? The Greens are so dogmatic and their sense being on a historic crusade to rid the world of fossil fuels so strong (and their understanding of and even respect for economics so weak) that I wouldn’t put it past them to drive the whole country into a disaster of epic proportions.
The country will be significantly more indebted after this winter than it has been at any time in the last forty years and at a time when that debt, especially if you include all the “off-balance sheet” pension fund and welfare system liabilities were already sky high. Germany can afford to be more indebted relative to other countries because of its deep savings pool and docile public. The drive to deeper European unity will continue because that is the only option open to them although the strain of maintaining that economically ruinous protection racket is getting increasingly unbearable. Any system that seeks to suspend the economic laws of gravity because they are politically uncomfortable (ie the whole of the West) will eventually succumb to those very laws and be overwhelmed by them. Like pygmies killing a hippopotamus, eventually they will wound and then destroy the money making behemoth at the centre of the EU distribution circus.
Germany will have to start rebuilding its military capacity after decades of burnishing its pacifist image. Olaf Scholz - the new Chancellor’s - recent €100 billion of extra funding for armaments and defence spending is just a taste of what is to come. However, several decades of NOT having to either pay their own security way or have to take any robust real-world responsibility fully to engage in military and defence activities, has left German politicians bereft of military / defence experience. They literally have no idea what they are doing in this arena.
With Nordtsream pipelines now hobbled and LNG terminals a way off completion, German energy costs will remain prohibitively high. Expect the nationalisation (in all but name) of the regional energy companies who are bearing the brunt of the long term contracts (2 years is the norm) issued to German businesses at a fixed rate before the 10 fold increase in gas prices early this year (think bank balance sheets lending long and refinancing short). The fate of Uniper, the largest German energy trading and import company, now nationalised, is just a taste of what is to come.
Off the back of that and coming so soon on the heels of the agonizing COVID induced supply chain issues in every component of industrial production you can think of, private sector Mittelstand balance sheets are going to be screaming in agong and severely depleted coming out of the winter. The deficit funding available may ensure that they stay afloat during the coming months but that is simply storing up trouble for later. Given that the bulk of Germany’s Mittelstand businesses are manufacturing something which requires substantial energy input (glass more than aluminium and plastic extrusion more than bending steel) and given that pre-crisis P&Ls had energy costs approximating to 6-7% of revenues and somewhere between 3% and 7% net operating margins, a doubling of energy costs would more than wipe out the profitability of most companies and a sustained period of losses would wipe out the equity of all but the most conservatively financed operations. Against that background, the current 10x increase in spot gas prices from €4,5 per Kw/h to over €48 per Kw/h is quite simply ruinous.
It was not always thus. I came across this graphic from the mid 1970s which showed the political consensus around Germany’s energy sourcing over the next decades.
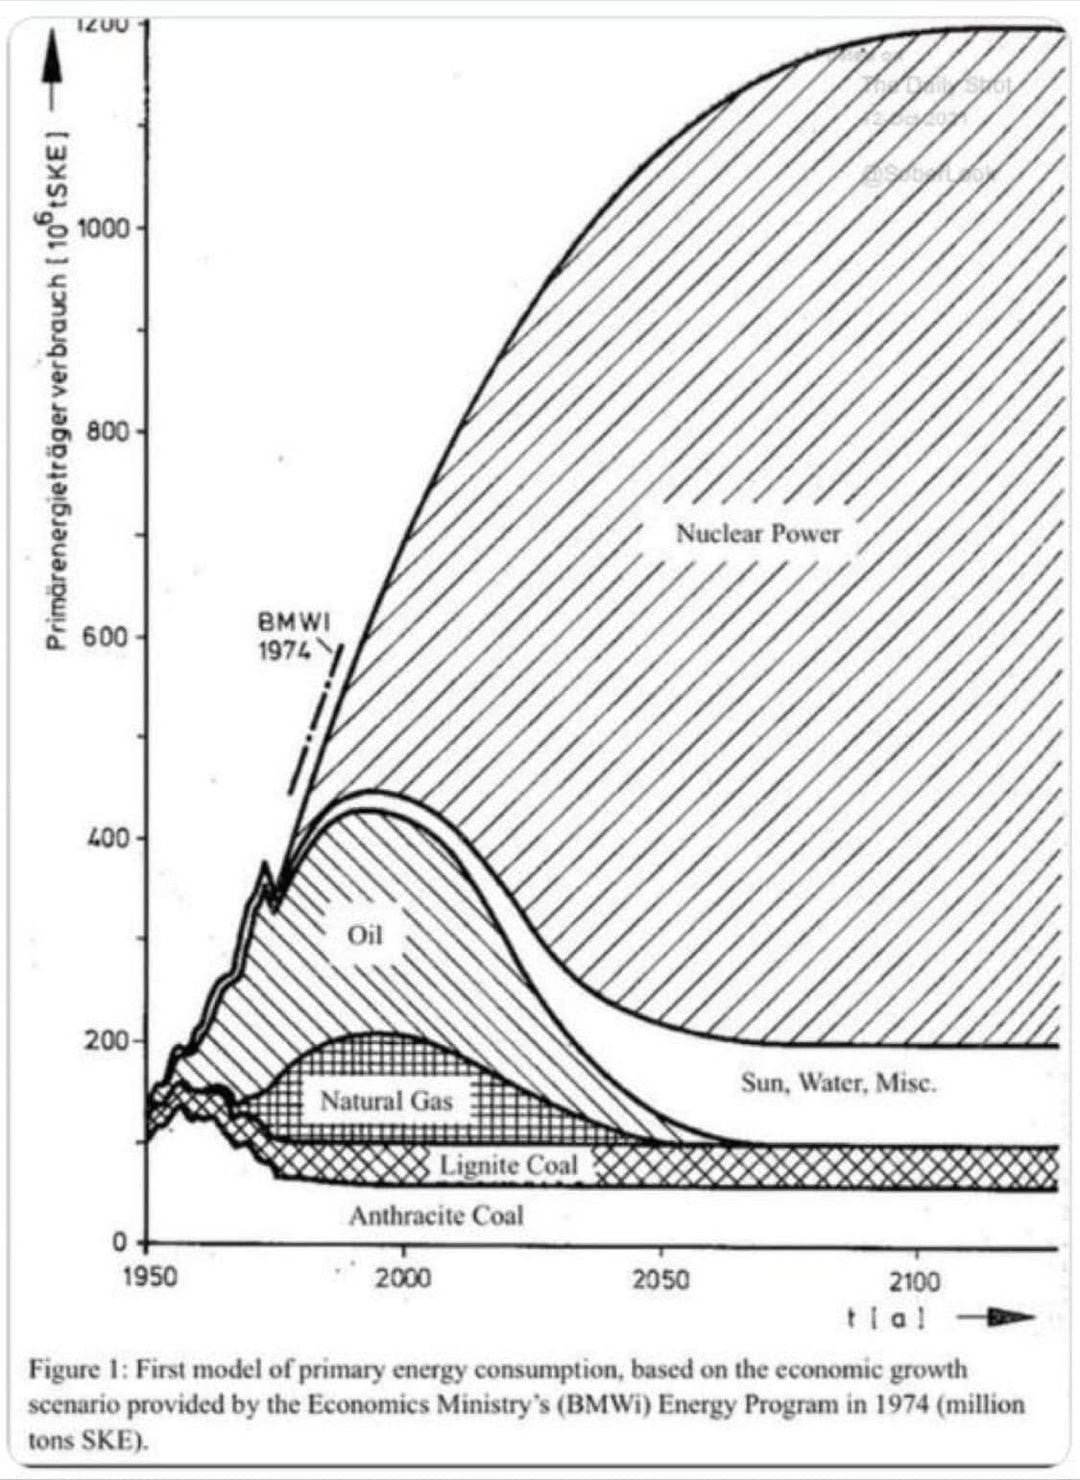
People were smarter then apparently.
I am not prone to playing Cassandra and don’t really enjoy the role, but this crisis and the responses to it are defying my ability to see an acceptable, prosperity-preserving outcome to the debacle. We are so used to endgame aversions by our governing institutions through the opening of the money spigot to douse the flames of catastrophe, that we are inured to the possibility of that gambit not working. As Luke Gromen and others have recently been at pains to point out - energy is the ultimate currency behind every government and economy and when it becomes short in supply, things stop working no matter how high you turn up the monetary firehouse.
When I read an article such as this I feel I know and understand more than 95% of the educated population on the subject.
It's like listening to Neil MacGregor talking about an ancient artifact in the British Museum. New unexplored worlds open up.
Steven, thank you very much for this. Will share this widely.
Wow, I thought at first you were going to provide a way forward, but your conclusion supports my worst fears. This is the ultimate conflict between the virtual and the physical. Even Germany cannot buy their way out of the looming crisis